Southwest Houston Neighborhoods: What the Market Is Actually Doing in 2026
There is a particular kind of market commentary that treats every month as either a boom or a crash. Southwest Houston in 2026 is neither, and the reality is more useful than either headline.
What we are seeing is a market that has normalized after four strange years, with more inventory than at any point in the record, prices holding roughly flat, and buyers who finally have time to think. Underneath that surface, the neighborhoods on this side of town are behaving quite differently from one another — and understanding those differences is most of what matters if you are buying or selling here.
The Regional Picture First
The Houston Association of Realtors reported 40,750 active single-family listings in July 2026, the highest level HAR has ever recorded, up 3.4% year over year. That is the headline number, and it sounds alarming until you look at what sat next to it.
Sales rose 1.6% over the same period, to 8,340 homes. Pending sales climbed 2.6%. The median price edged up 0.6% to $340,000, and the average rose 1.9% to $440,816. Over the trailing twelve months, Houston recorded 89,367 single-family sales, up 2.5% from the year before.
More homes for sale, more homes selling, prices essentially flat. That is what a balanced market looks like, and Houston has not had one in a while. Months of supply has been running in the 4.7 to 5.2 range through 2026, up from the acutely tight conditions of 2021 and 2022.
The comparison that puts it in perspective comes from HAR’s chief economist, Dr. Ted C. Jones: Houston sales volume has returned to normal pre-pandemic levels, while nationally, single-family sales for the twelve months ending July 2026 ran about 20% below the equivalent pre-pandemic period. Houston recovered. Much of the country has not.
Affordability has helped. Freddie Mac’s 30-year fixed averaged 6.33% in April 2026, down from 6.73% a year earlier. On a median-priced home, that difference is roughly $100 a month.
Southwest Houston Is Not One Market
Zoom in and the averages break apart quickly.
Sugar Land remains the anchor of the established southwest market. Median pricing sits around the mid-$400s, and inventory for well-priced homes has stayed considerably tighter than the regional average — closer to two months than five. That is still seller’s territory in a metro that has broadly tilted toward buyers. Sugar Land’s advantage is structural: it is largely built out, so supply cannot expand the way it can further west, and Fort Bend ISD zoning plus corporate proximity keeps demand steady.
Missouri City offers a meaningful price step down from Sugar Land for comparable square footage, with pockets of genuine value in older sections and newer development in Sienna and the surrounding area. It has historically appreciated more slowly than Sugar Land but also draws a wider range of buyers.
Richmond and Rosenberg sit at the affordability end of the county and have absorbed a great deal of the region’s new construction. Prices are lower, lot sizes are often larger, and the tradeoff is longer commutes and MUD-heavy tax structures in the newer communities.
Katy has been one of the stronger performers. HAR price trend data showed a median of $355,000 in May 2026, up 5.6% year over year, with homes selling in a median of 22 days against 18 a year prior. Katy is doing something unusual for 2026: appreciating while the broader market flattens.
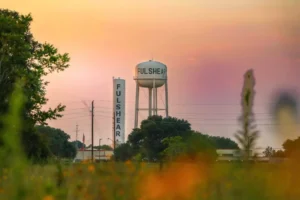
Fulshear is the growth story, and its own separate case. As the fastest-growing city of its size in the country three years running, it has the deepest new-construction pipeline and correspondingly the most builder competition for resale sellers.
Countywide, Fort Bend’s median has been running in the mid-$370s, with days on market lengthening considerably — one January 2026 measure showed 84 days against 55 the prior year. That lengthening is the clearest signal in the data. Homes still sell. They just take longer, and mispriced ones sit.
The Price Bands Behave Differently Too
One of the more counterintuitive patterns in Fort Bend this year: homes between $600,000 and $1 million have been moving faster than homes under $300,000. Across the metro, sales above $1 million rose 17.1% year over year in June.
Meanwhile the $300,000 to $600,000 band remains by far the largest and most active segment by volume. And the townhome and condo market is a different world entirely, with supply running above ten months and average days on market past 120 — the softest segment in the region by a wide margin.
If you are selling, your neighborhood average is less relevant than your price band within your neighborhood. Those two things can point in opposite directions.
What the Influx Is Actually Doing
Texas added 391,243 residents in the year to July 2025, more than any state. Much of that landed in the Houston metro, and a disproportionate share of it landed on this side of town.
The composition matters as much as the volume. Fort Bend County has now overtaken Harris as the most racially and ethnically diverse county in the region, with the highest share of foreign-born residents at 30.7%, a majority of them from Asia. In Fort Bend, more than one in three residents speaks a language other than English at home. Median household income in the county exceeds $100,000.
That demographic profile has two practical effects on the market.
First, it broadens the buyer pool in ways that stabilize demand. Southwest Houston draws from the Texas Medical Center, the Energy Corridor, corporate relocations, and international migration simultaneously. When one of those channels slows, the others rarely slow at the same time. That diversification is a large part of why this market does not swing as hard as single-industry metros.
Second, it shapes what sells. Multigenerational floor plans, homes near specific places of worship, proximity to particular grocery and retail corridors — these move properties here in ways that a purely national market model would miss entirely. Two identical houses a few miles apart can perform very differently for reasons that have nothing to do with square footage.
It is worth naming the counterweight honestly: net international migration to the United States fell roughly 55% nationally in 2025, and immigration to Texas dropped about 48%. Domestic migration into Texas also cooled sharply from its 2022 peak. Growth continues, but at a slower pace than the last few years, and anyone modeling future demand on 2021-2022 numbers is using the wrong baseline.
Why This Market Has Been Steady
Houston has a structural feature that most large metros lack: supply responds quickly to demand. There is little zoning, land is available in most directions, and builders can deliver quickly.
This is the actual reason Houston came through 2008 far better than Phoenix or Las Vegas, and it is why prices here have held roughly flat through a period when several Sun Belt markets have declined outright.
But the same mechanism works in both directions, and this is the part that rarely makes it into marketing. Elastic supply dampens bubbles, and it also caps appreciation. Houston does not produce the windfalls that supply-constrained coastal markets occasionally deliver. What it produces is steadiness. Over long holding periods that has been a good trade for most owners. Over short ones it can be an unremarkable one.
It Is Not Foolproof, and Anyone Who Says Otherwise Is Selling You Something
Real estate is not a guaranteed asset, here or anywhere. A few things that genuinely go wrong in this market:
Flooding. Harvey reshaped development patterns and buyer behavior across the region for good reason. Flood history and floodplain status are not paperwork items. They affect insurability, resale, and lender requirements. Check them on every property, including ones outside mapped floodplains.
Insurance costs. Texas premiums have risen substantially in recent years. A quote you receive today may not resemble what the prior owner has been paying, and it belongs in your affordability math before you write an offer.
The tax and MUD stack. Combined rates in newer master-planned communities can run well above 3%. On a $500,000 home, the spread between a low-rate and high-rate community can exceed $3,000 a year — often more than the price difference that drove the choice.
Short holding periods. Transaction costs plus flat pricing means selling within two or three years frequently produces a loss, regardless of how good the market looked when you bought.
New-construction competition. If you buy in a community that is still selling new phases, you may eventually list against a builder who can offer rate buy-downs and incentives that you cannot match.
None of this is an argument against buying. It is an argument for buying with a realistic holding period, a verified tax bill, and an insurance quote in hand. The people who get hurt in this market are almost never the ones who did those three things.
And Still — Life Is Good Here
Set aside the spreadsheets for a moment.
Southwest Houston is a place where a family can own a home with a yard on an ordinary income, where the schools are genuinely good in most of the county, where you can eat food from four continents within a mile of your house, and where your neighbors came from everywhere and mostly get along. There is no state income tax. The economy is diversified enough to have absorbed shocks that flattened other regions. Winters are short.
The heat is real. The traffic is real. Nobody here will pretend otherwise. But the fundamental bargain — space, opportunity, and a genuinely welcoming set of communities, at a price that most of America’s growth markets abandoned a decade ago — is still on the table on this side of Houston.
That bargain is why people keep arriving. The market data is just the arithmetic of that fact.
Where to Start
If you are weighing neighborhoods, trying to understand what a specific home would actually cost you monthly once taxes and insurance are included, or deciding whether this is the right time to list, we are glad to walk through the numbers for your specific situation. For decisions with significant financial consequences, it is worth speaking with your own tax and financial advisors as well.